Venture Capital Tokenization: LP Access & Fund Liquidity
Venture capital operates on a structural friction between long-term value creation and investor liquidity needs. Fund managers deploy capital into private technology companies that require years to mature, forcing limited partners to lock up their money for a decade or longer. This illiquidity premium has historically restricted the asset class to large institutional investors and ultra-high-net-worth individuals who can afford to park millions of dollars in inaccessible vehicles. Venture capital tokenization introduces a mechanism to resolve this friction by converting fund shares into digital assets that can trade on secondary markets. By issuing tokens on a blockchain that represent legal ownership in a fund, managers can offer interim liquidity options while maintaining the stable capital base required to support early-stage companies. The transition from paper contracts to programmable digital shares fundamentally alters the mechanics of private market investing. This analysis examines how tokenized venture investment structures operate in practice, reviewing the regulatory frameworks, the secondary market performance, and the realities of fractionalizing private equity funds.
Context of the venture capital liquidity problem
Venture capital funds typically require investors to lock up their capital for ten to twelve years while charging high minimum investments often exceeding one million dollars. Tokenization addresses this structural illiquidity by converting limited partner interests into digital assets that can trade on secondary markets, offering a potential exit before the fund naturally dissolves.
The traditional venture capital model relies on a closed-end fund structure designed to match the lengthy gestation period of private startups. When limited partners commit capital to a fund, they agree to a schedule of capital calls drawn down over an active investment period of three to five years. The fund then enters a harvesting phase where the general partners attempt to guide the portfolio companies toward an acquisition or initial public offering. During this entire lifecycle, limited partners have almost no ability to access their capital or sell their stakes. Traditional secondary markets for private fund interests exist, but they operate through opaque broker networks with high transaction costs and steep discount rates. This structural illiquidity forces investors to endure the J-curve effect, where fund returns are negative in the early years due to management fees and initial startup failures, before any potential gains materialize near the end of the decade.
Regulatory frameworks heavily influence these rigid fund structures and high barriers to entry. In the United States, venture funds typically operate under the Securities and Exchange Commission’s Regulation D, specifically Rule 506(b) or 506(c), which exempts them from registering as public securities. To maintain this exemption, funds must restrict their investor base to accredited investors. Furthermore, to avoid registering as an investment company, venture funds rely on Section 3(c)(1) or Section 3(c)(7) of the Investment Company Act of 1940. Section 3(c)(1) limits a fund to 100 beneficial owners, forcing managers to set extremely high minimum investment thresholds to reach their target fund size. Section 3(c)(7) allows up to 2,000 investors but requires them to be qualified purchasers holding at least five million dollars in investments. These combined regulatory constraints create a system where only the wealthiest entities can participate.
General partners also prefer fewer, larger limited partners because servicing hundreds of individual investors creates massive administrative overhead. Managing capital calls, tax reporting, and distributions for a fragmented investor base requires significant back-office resources. This operational reality, combined with the legal caps on investor numbers, means traditional venture funds routinely set minimum check sizes between two hundred fifty thousand and five million dollars. Investors looking to tokenize startup equity directly face similar hurdles, but fund-level tokenization attempts to solve the problem by pooling capital through a single digital infrastructure. By automating the compliance and cap table management through smart contracts, tokenization theoretically removes the administrative burden that historically necessitated high investment minimums.
What happened when venture funds embraced tokenization
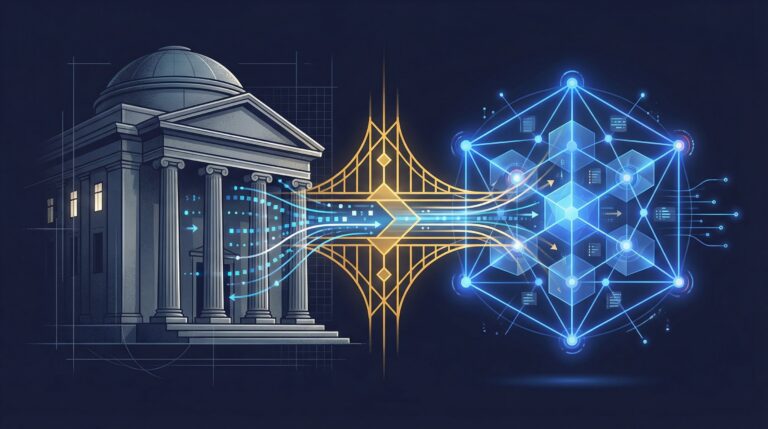
Fund managers implemented venture capital tokenization by creating special purpose vehicles that hold traditional limited partnership interests and issue corresponding digital tokens on a blockchain. Platforms manage investor onboarding, compliance, and secondary market trading for these tokenized fund shares, ensuring all transfers automatically adhere to underlying securities regulations.
The mechanics of a tokenized VC fund rely on a legal wrapper, usually a special purpose vehicle or a master-feeder structure. The general partner establishes a traditional venture fund entity that holds the actual startup equity. They then create an associated feeder fund that issues digital tokens instead of traditional paper partnership agreements. Each token represents a proportional fractional share of the feeder fund’s net asset value. Smart contracts embedded in the tokens enforce regulatory restrictions automatically. If a tokenized fund operates under Regulation D, the smart contract will block any secondary transfer during the mandatory one-year lock-up period. After the lock-up expires, the contract will only permit transfers to digital wallets that have passed identity verification and accredited investor checks. You can read more about how these compliance engines operate in our Securitize review, as they provide the core infrastructure for issuing and managing these digital securities.
Blockchain Capital pioneered this model in 2017 with the launch of the BCAP token. The firm raised ten million dollars by issuing tokens that represented indirect fractional non-voting economic interests in their third venture fund. The offering demonstrated that digital assets could successfully map to traditional private equity structures while complying with US securities laws. Following this proof of concept, SPiCE VC launched a fully tokenized venture fund designed from inception to provide early liquidity to its investors. Unlike traditional funds where the general partner controls all distribution timelines, SPiCE VC structured their tokens to trade on compliant alternative trading systems. This allowed their limited partners to sell their positions to other verified investors based on the fund’s stated net asset value and secondary market demand.
Tracking the net asset value of a tokenized venture fund presents distinct operational challenges. Public market tokens track highly liquid assets with continuous pricing data. Venture capital portfolios consist of illiquid private companies that are typically valued on a quarterly basis using delayed metrics. When venture capital LP tokens trade on a secondary market, buyers and sellers must negotiate prices based on outdated or estimated net asset values. If a fund holds a breakout company that recently raised at a higher valuation, the token price might trade at a premium to the last reported NAV. Conversely, if the broader technology market declines, the tokens may trade at a steep discount before the fund officially writes down its portfolio. Investors learning how to invest in tokenized assets must understand that the token price on a secondary exchange reflects immediate market sentiment rather than a precise real-time audit of the underlying startups.
Results from early tokenized venture investments
The initial results of tokenized venture investments demonstrate significant reductions in minimum capital requirements, dropping from traditional levels of two hundred fifty thousand dollars down to ten thousand dollars. Secondary market platforms have successfully enabled early liquidity for limited partners, though trading volumes remain concentrated among a small number of active funds.
The most immediate and measurable result of venture fund tokenization is the drastic reduction in investment minimums. Because smart contracts automate cap table management and distribution routing, fund managers can accept much smaller checks without increasing their back-office costs. Several tokenized venture vehicles have lowered their entry thresholds to ten thousand or twenty-five thousand dollars. This reduction expands the addressable market of potential limited partners significantly. While these investors must still meet accredited investor definitions in the US, the lower minimums allow them to build diversified venture portfolios rather than concentrating all their alternative capital into a single fund. This democratization aspect has driven early adoption among high-net-worth individuals who were previously priced out of top-tier venture access.
Secondary market performance for VC fund liquidity tokenization has shown mixed but promising results. Tokens like BCAP and SPICE have successfully traded on regulated alternative trading systems, proving that the technical and legal plumbing works. Limited partners have successfully exited their positions years before the funds liquidated their underlying portfolios. However, liquidity remains relatively thin compared to public equities. Trading volumes fluctuate based on broader crypto market sentiment and specific announcements regarding the fund’s portfolio companies. Because the buyer pool is restricted to other accredited investors who have completed onboarding with the specific trading platform, the bid-ask spreads can be wide. Understanding the tokenization market size helps contextualize these early trading volumes, as the infrastructure for institutional secondary trading is still being built.
Institutional interest in tokenized venture funds is accelerating as traditional asset managers observe these early results. According to a 2024 report by Boston Consulting Group, the tokenization of illiquid assets, including private equity and venture capital, could reach sixteen trillion dollars by the end of the decade. Major financial institutions are not necessarily interested in the democratization aspect; they are interested in the operational efficiency and the ability to manage their own balance sheet liquidity. A pension fund or endowment holding tokenized LP interests could theoretically pledge those tokens as collateral for short-term borrowing, a process that is highly cumbersome with paper-based partnership agreements. This institutional pull is driving the development of more robust secondary venues and standardized valuation frameworks.
Lessons learned and regulatory considerations
Market participants learned that venture capital tokenization introduces unique risks including valuation opacity, adverse selection on secondary markets, and complex tax reporting requirements. Regulatory compliance remains strictly enforced, requiring all secondary market buyers to meet the same accredited investor or qualified purchaser standards as the original fund participants.
One of the primary lessons from early tokenized funds is the persistence of the J-curve problem in secondary trading. If a limited partner decides to sell their tokens in year two or three of a venture fund, they are selling a portfolio of immature companies that have not yet realized their growth potential. Secondary market buyers will naturally demand a steep discount to acquire these unproven assets. This dynamic means that while tokenization provides the option for early liquidity, exercising that option often comes at a significant financial cost. Furthermore, secondary markets face the risk of adverse selection. Buyers may assume that if a limited partner is eager to sell their tokens, they might possess negative asymmetric information about the fund’s underlying portfolio. Navigating these tokenized asset risks requires buyers to conduct deep due diligence rather than relying solely on the fund’s stated net asset value.
Regulatory realities have also tempered early expectations about global, frictionless trading. A digital token representing a venture fund share is a security. It does not bypass the Securities Act of 1933 or the Investment Company Act of 1940. Every secondary market transaction must comply with the regulations of the jurisdictions where the buyer and seller reside. If a US-based fund tokenizes its shares under Rule 506(c), the secondary market platform must verify the accredited status of every subsequent buyer. If the fund relies on Section 3(c)(7), every secondary buyer must be a qualified purchaser. These strict compliance requirements prevent venture tokens from trading on open, permissionless decentralized exchanges. Instead, they must trade within walled gardens managed by registered broker-dealers and regulated alternative trading systems. You can review our tokenization glossary for precise definitions of these regulatory classifications.
Tax reporting introduces another layer of complexity that the industry is still working to standardize. Traditional venture funds issue Schedule K-1 forms to their limited partners annually, detailing their share of the fund’s income, losses, and capital gains. When fund shares are tokenized and traded on a secondary market, tracking the exact holding periods and cost bases for multiple buyers and sellers becomes highly complex. The fund administrator must reconcile the blockchain ledger with traditional tax reporting software to ensure accurate K-1 generation for everyone who held the token during the fiscal year. Solutions are emerging to automate this reconciliation, but it remains a friction point for fund managers considering tokenization.
The outlook for venture capital tokenization points toward deeper integration with traditional financial plumbing. The technology has proven its ability to lower minimums, automate compliance, and facilitate secondary transfers. The next phase of adoption relies on the expansion of regulated secondary markets and the standardization of valuation protocols. As more high-quality general partners issue tokenized funds, the secondary markets will attract more institutional buyers, tightening bid-ask spreads and providing truer price discovery. Venture capital tokenization does not change the fundamental difficulty of selecting winning startups, but it successfully modernizes the antiquated legal structures that have governed private market investing for decades.
Frequently Asked Questions
What is venture capital tokenization?
Venture capital tokenization is the process of converting limited partnership interests in a VC fund into digital tokens on a blockchain. These tokens represent legal fractional ownership of the fund, allowing investors to trade their shares on compliant secondary markets instead of waiting for a ten-year lockup to expire.
How does tokenization change VC fund minimums?
Tokenization drastically lowers the minimum investment required to participate in venture capital funds. By using smart contracts to automate compliance and cap table management, fund managers can efficiently accept investments as low as ten thousand dollars, compared to traditional minimums of two hundred fifty thousand dollars or more.
Can anyone buy tokenized venture capital funds?
No, tokenized venture funds are subject to strict securities regulations and are not available to the general public. In the United States, buyers must typically verify their status as accredited investors or qualified purchasers before they are legally permitted to purchase or trade these digital securities.
How do you value a tokenized VC fund on the secondary market?
Tokenized VC funds are valued based on the market demand for the tokens relative to the fund’s reported net asset value. Because the underlying startups are illiquid private companies, secondary market token prices may trade at a premium or a discount to the official NAV depending on investor sentiment.