STO Marketing Strategy: How to Attract Investors Compliantly
2026 Issuer Marketing Reality: Over 70% of failed Security Token Offerings (STOs) fail not from smart contract flaws, but from violating U.S. SEC general solicitation rules or underbudgeting investor acquisition costs (CAC). Under Regulation D Rule 506(c) and Regulation A+, issuers can run public digital campaigns, paid LinkedIn/X funnels, and webinars—provided 100% of US subscribers pass independent third-party accreditation or broker-dealer suitability checks before minting tokens.
Marketing a security token offering requires founders to unlearn almost everything they know about conventional cryptocurrency promotion. When you issue a security token, you are selling regulated financial instruments, not consumer products or utility tokens. Securities regulators do not grade on a curve for blockchain technology, meaning that every public statement, tweet, and pitch deck must comply with strict investor solicitation laws. An effective STO marketing strategy balances the aggressive need for capital acquisition with the absolute necessity of regulatory compliance. Founders who attempt to run an ICO-style hype campaign for a registered security will quickly face enforcement actions, platform delistings, and unraveled funding rounds.
The challenge of security token offering marketing lies in identifying and converting qualified investors within a highly constrained communication environment. Traditional venture capital marketing relies heavily on private networks, while retail crowdfunding depends on mass-market digital advertising. Tokenization sits at the intersection of these two worlds, requiring a bifurcated approach that targets institutional capital through direct outreach while simultaneously building a compliant public narrative. Understanding how to market STO campaigns effectively means mastering the specific rules of your chosen regulatory exemption before spending a single dollar on advertising.
This guide outlines the practical mechanics of STO investor acquisition. It covers the legal boundaries of public solicitation, the structure of institutional pitch materials, the execution of investor roadshows, and the realistic costs associated with funding a tokenized asset. Founders must approach this process with clear expectations regarding timelines, conversion rates, and the mandatory involvement of licensed financial intermediaries.
Navigating SEC regulations for security token marketing
An STO marketing strategy is strictly governed by the SEC exemption chosen for the raise. Regulation D Rule 506(b) prohibits all public advertising, while 506(c) allows general solicitation if all investors are verified as accredited. Regulation CF permits broad marketing through registered funding portals, and Regulation A+ offers the widest promotional latitude following SEC qualification.
The most critical decision a founder makes regarding tokenization marketing channels is selecting the appropriate regulatory framework. Under Regulation D Rule 506(b), the SEC strictly enforces a prohibition on general solicitation through Rule 502(c). This means founders cannot publicly advertise the offering, post about the raise on social media, speak about the investment terms at public conferences, or use mass-market digital channels. Marketing a 506(b) offering relies entirely on pre-existing substantive relationships. Founders must depend on warm introductions, private investor networks, family office connections, and partnerships with licensed private placement agents. The communications must remain private, targeted, and restricted to individuals with whom the issuer or their broker-dealer has an established history.
Conversely, Regulation D Rule 506(c) fundamentally changes the marketing approach by permitting general solicitation. Founders utilizing this exemption can run digital advertising campaigns, host public webinars, and discuss the offering openly on social media platforms. However, this freedom comes with a strict compliance burden requiring the issuer to take reasonable steps to verify that every participating investor holds accredited status. You can market to the entire world, but you can only accept capital from verified wealthy individuals or institutions. This dynamic heavily influences how marketing dollars are spent, as broad awareness campaigns often yield high volumes of unqualified leads that waste administrative resources. Understanding the nuances between these approaches is essential when reviewing a Reg D vs Reg CF vs Reg A+ comparison for your specific capital needs.
Retail-focused exemptions offer different marketing parameters that require specific infrastructure. Regulation CF allows founders to market to non-accredited investors, but the SEC mandates that all offering activities and investments flow through a registered funding portal or broker-dealer. Marketing materials for Reg CF can direct potential investors to the portal, but the issuer’s direct communications are limited to basic factual notices about the offering. Regulation A+ provides the closest equivalent to a traditional public IPO marketing campaign, allowing companies to
2026 SEC Exemption Marketing & General Solicitation Matrix
Before launching a landing page, publishing yield projections on X (formerly Twitter), or sponsoring an institutional newsletter, founders must align their promotional channels with their exact securities exemption. Promoting a private placement under the wrong exemption triggers an immediate loss of safe harbor and a mandatory 6-month SEC integration cooling-off period. Review our US SEC tokenization regulation guide and US legal requirements breakdown to structure your exemption before spending marketing capital.
| SEC / Global Pathway | Public Advertising & Social Media Allowed? | Permitted Investor Audience | Mandatory Verification / Gatekeeping | Typical Investor CAC (2026 Benchmark) |
|---|---|---|---|---|
| Reg D Rule 506(c) | Yes — Paid ads, PR, podcasts, X/LinkedIn, public pitch decks | Verified US Accredited Investors ($200K income / $1M net worth) | Strict 3rd-party verification (CPA letter, tax returns, VerifyInvestor) prior to closing | $450 – $1,200 per funded accredited wallet ($25K–$100K ticket) |
| Reg D Rule 506(b) | No — Strictly prohibited; zero public solicitation or open webinars | Accredited + up to 35 sophisticated non-accredited investors | Substantive, pre-existing relationship documented prior to offering launch | Relationship-driven (private placement agents charge 4%–7% success fee) |
| Regulation CF | Yes (Restricted) — “Tombstone” ads must route traffic to the FINRA Funding Portal | All US Retail & Accredited Investors (up to $5M annual cap) | All offering terms and communications must live inside the portal (Republic, StartEngine) | $65 – $180 per retail investor ($500–$2,500 average ticket) |
| Regulation A+ (Tier 2) | Yes — Full retail performance marketing & “Testing the Waters” (Rule 255) | All US Retail & Accredited Investors (up to $75M annual cap) | SEC Form 1-A qualification + mandatory disclaimers on pre-qualification ads | $140 – $350 per funded investor ($1,500–$10,000 ticket) |
| Regulation S (Offshore) | Yes (Geo-Fenced) — Permitted outside the US (“no directed selling efforts” in US) | Non-US Persons only (frequently paired with Reg D 506c) | IP geo-blocking of US traffic + non-US passport KYC via Tokeny or Brickken | $220 – $650 per international accredited subscriber |
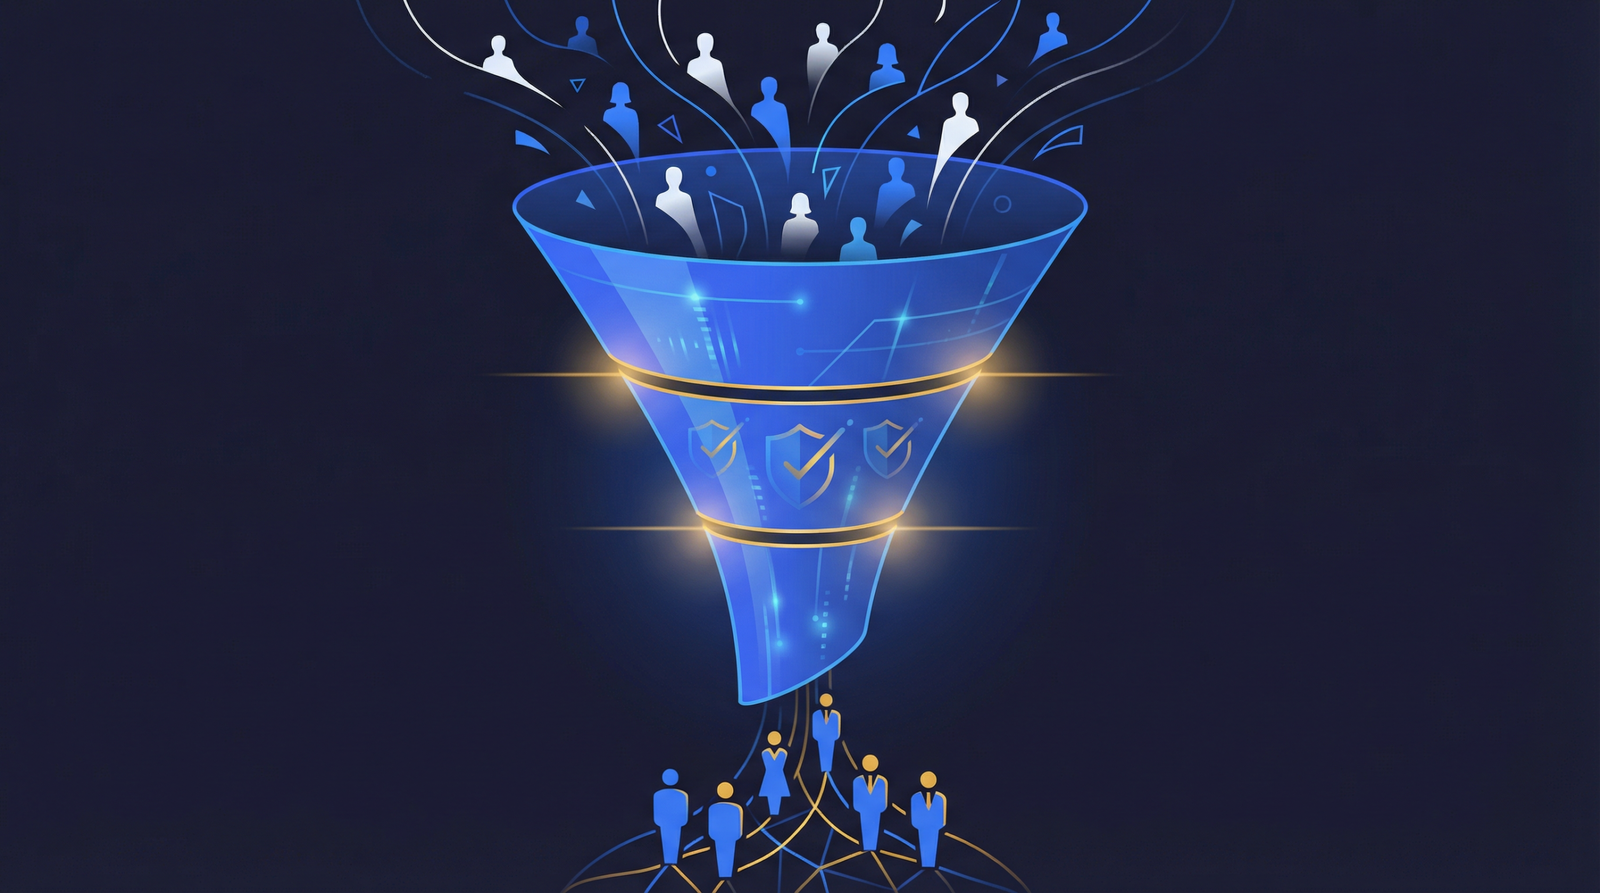
Building a Compliant 4-Stage Accredited Investor Acquisition Funnel
Unlike unregulated Web3 utility token launches that rely on Discord hype and speculative airdrops, regulated RWA and equity token raises require an institutional capital-markets funnel. Whether you are raising $5 million for a commercial real estate SPV or $25 million for a venture growth round (see our startup tokenization cost breakdown), high-converting issuers structure their investor journey across four auditable stages:
- Stage 1: Educational Thought Leadership & Asset Transparency (Top of Funnel): Publish verifiable data on the underlying asset class—such as historical net operating income (NOI), audited financial statements, custody architecture, and comparative yield spreads against US Treasuries. Institutional allocators ignore hype and respond to transparent risk-adjusted return metrics.
- Stage 2: Gated Data Room & Soft-Commit Registration (Middle of Funnel): Direct paid LinkedIn, newsletter, and PR traffic to an SEC-compliant landing page hosted on your issuance portal (such as Securitize, DigiShares, or Brickken). Require prospective investors to self-certify their jurisdiction (US Accredited vs. Non-US Reg S) before unlocking the Private Placement Memorandum (PPM) and smart contract audit reports.
- Stage 3: Automated KYC/AML & Rule 506(c) Accreditation (Conversion Layer): Integrate frictionless API verification (Parallel Markets, VerifyInvestor, or Sumsub) directly inside the investor dashboard. Every extra day of manual document review causes a 22%–30% drop-off in committed capital.
- Stage 4: Fiat-to-Stablecoin Subscription & Post-Issuance IR (Retention): Allow approved investors to fund via ACH, Fedwire, or USDC/USDT on identical terms, and maintain quarterly on-chain NAV reporting to build secondary market demand on regulated venues like tZERO ATS.
FINRA Rule 2210 & SEC Marketing Rule Pitfalls That Trigger Enforcement
When working with a registered broker-dealer or placement agent, all investor communications must comply with FINRA Rule 2210 (Communications with the Public) and the SEC’s modernized Marketing Rule. Founders routinely trigger compliance blocks by making three avoidable mistakes: (1) quoting projected target IRRs without presenting net-of-fee assumptions and downside risk disclosures in equal prominence; (2) implying that ERC-3643 or blockchain tokenization guarantees “instant 24/7 secondary liquidity” when secondary ATS order books may remain thin after lock-up expiration; and (3) paying unregistered crypto influencers or Telegram promoters transaction-based percentages of capital raised—a direct violation of Section 15(a) broker-dealer registration rules that grants investors an automatic statutory right of rescission.
Common Regulatory & Structuring Questions
Can I use social media to market my security token offering?
You can use social media to market your STO only if your regulatory exemption permits general solicitation, such as Reg D 506(c) or Reg A+. If you are raising under Reg D 506(b), any public social media posts about the offering violate SEC rules.
How much does it cost to acquire an investor for an STO?
The average customer acquisition cost for a security token offering ranges from $200 to $800 per funded investor. This cost fluctuates based on the asset class, the regulatory exemption used, and the effectiveness of the digital marketing funnel.
Do I need a broker-dealer to market my tokenized offering?
You are not strictly required to use a broker-dealer for all exemptions, but partnering with one is highly recommended for compliance and distribution. A registered broker-dealer can legally solicit investors, handle secondary market placements, and ensure marketing materials meet FINRA standards.
What is the typical KYC drop-off rate during STO onboarding?
Typical KYC completion rates for tokenized offerings range from 40% to 70%. Many interested retail and accredited investors abandon the process due to the extensive documentation required to prove identity and verify accredited status under strict securities laws.
References & Official Filings
- [1] Rule 502(c) of Regulation D – General Solicitation and General Advertising
- [2] Rule 506 of Regulation D – Exemption for Limited Offers and Sales Without Regard to Dollar Amount of Offering
- [3] State of Security Tokens 2024: Market Report and Investor Acquisition Data
- [4] FINRA Rules on Communications with the Public (Rule 2210)
- [5] Regulation Crowdfunding: A Primer for Small Businesses