AI and tokenization convergence: automated compliance and analytics
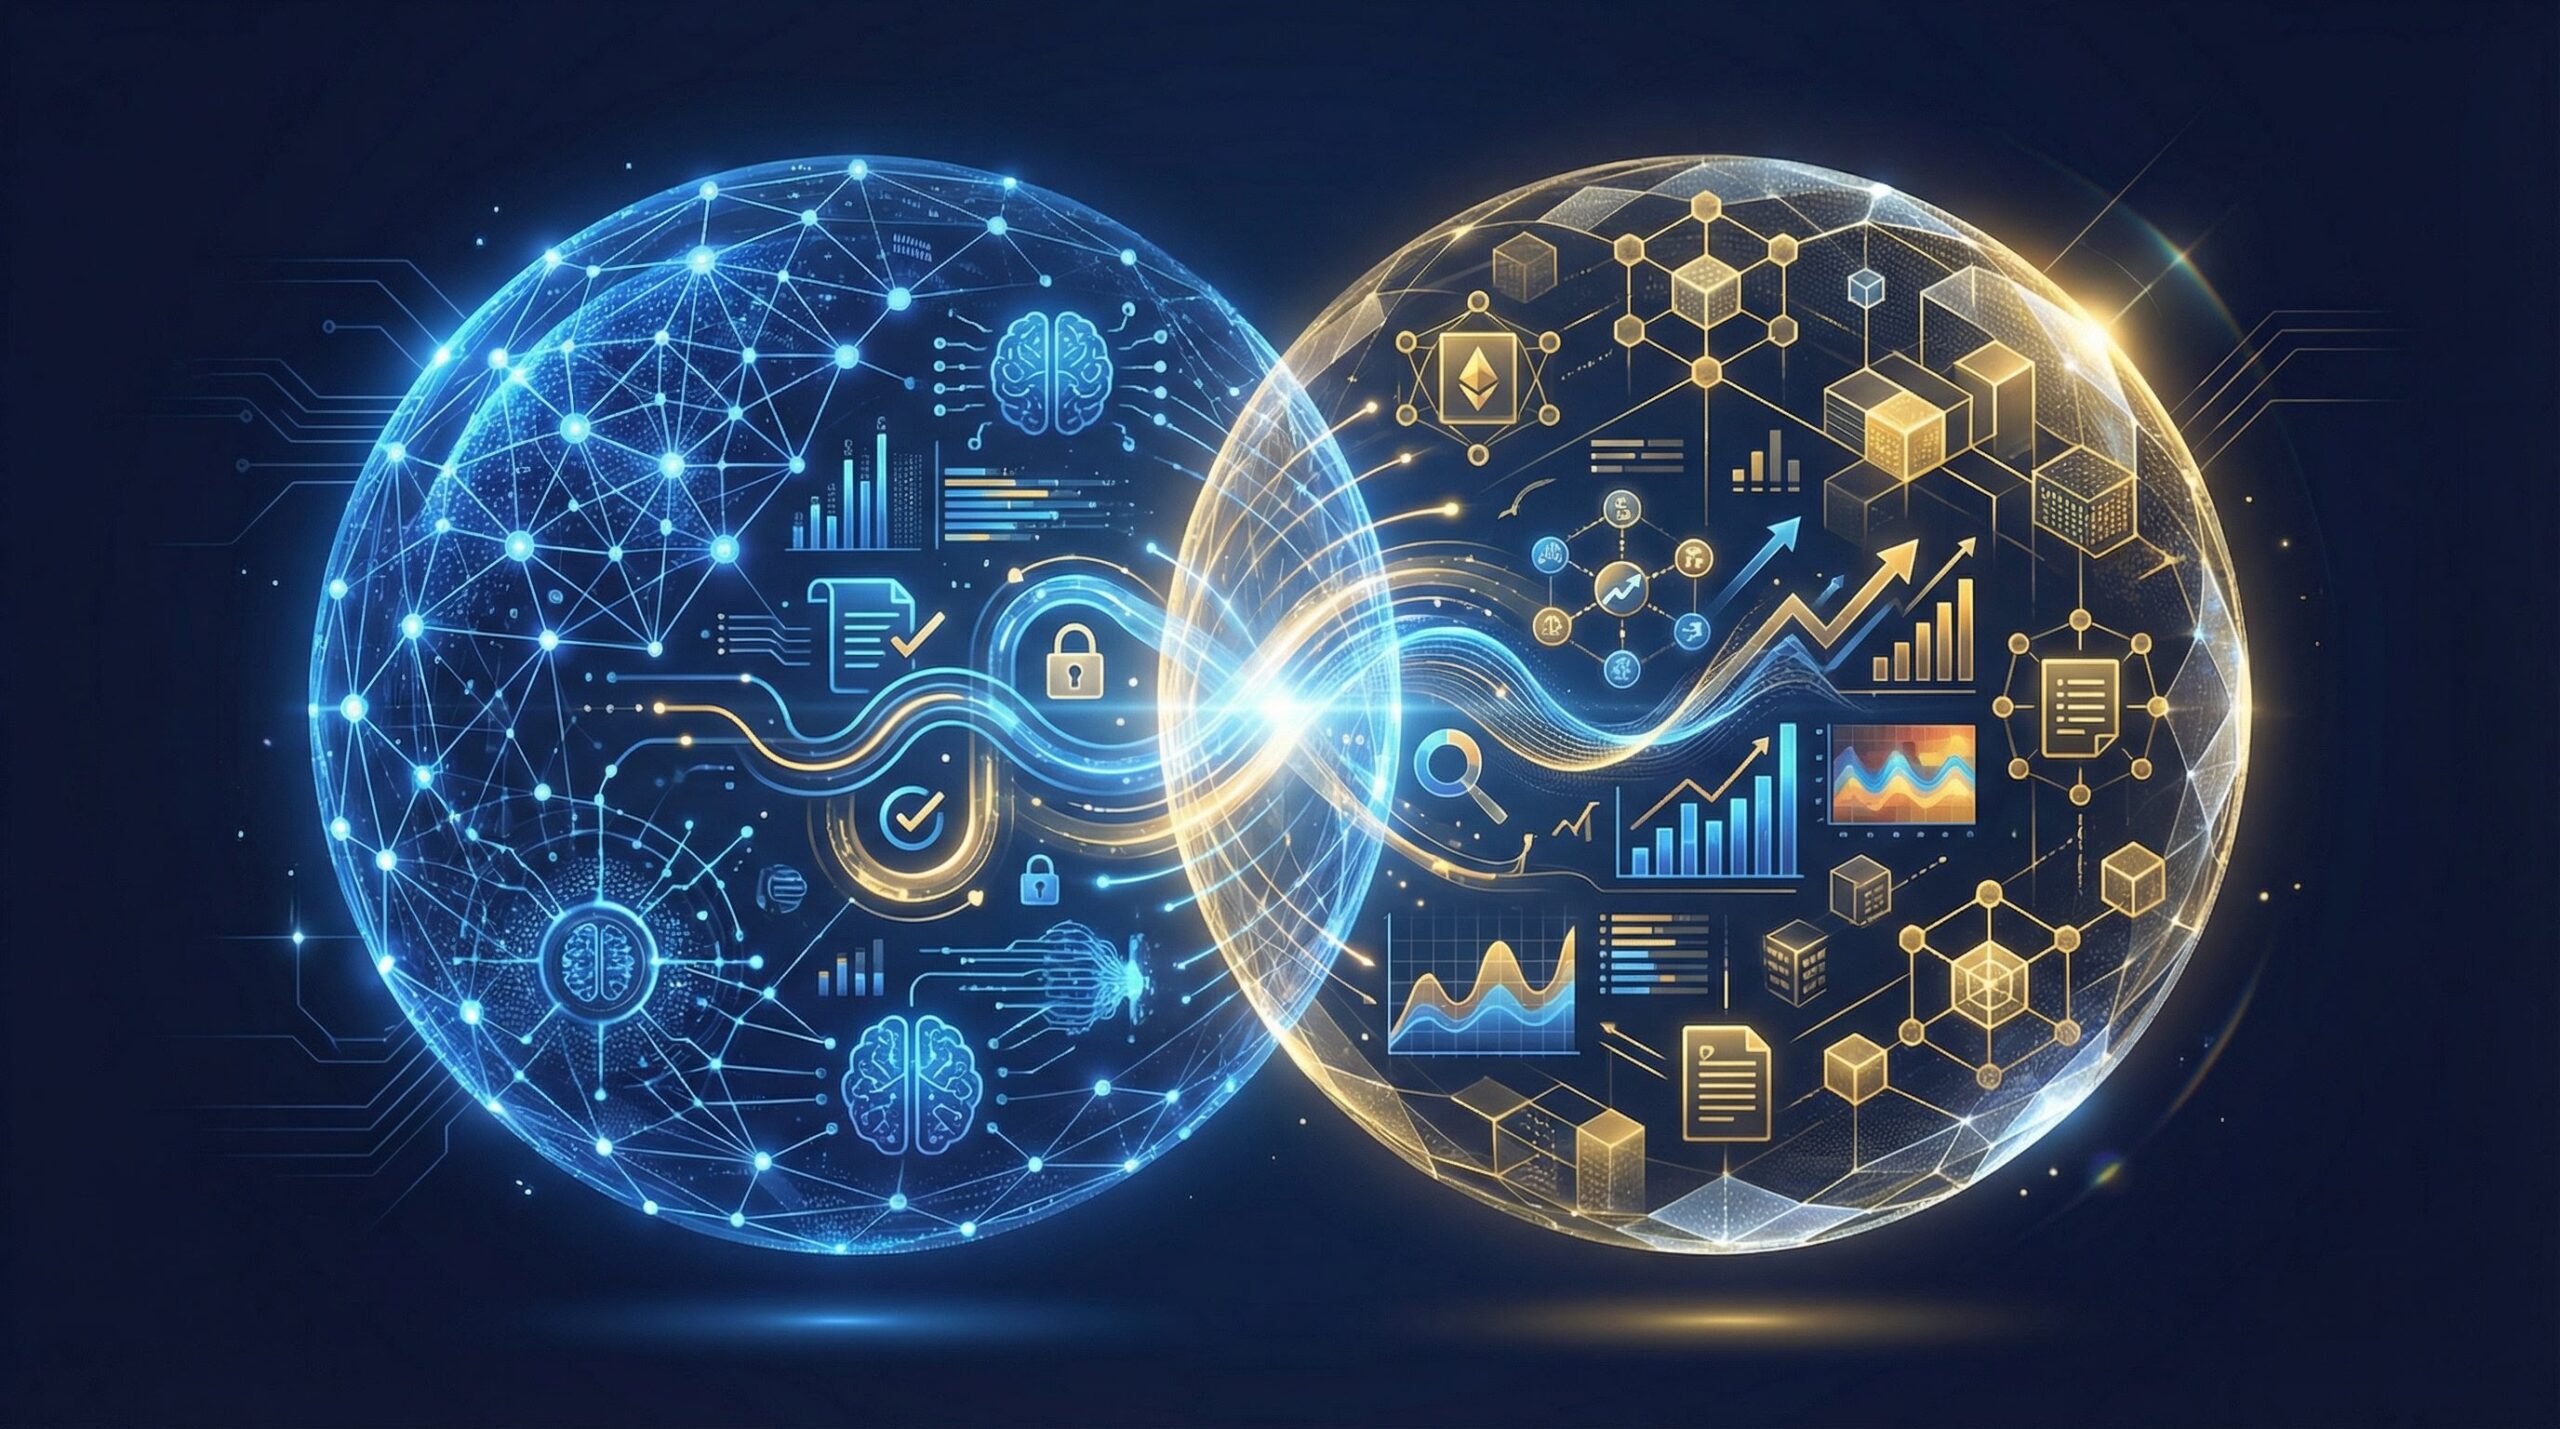
The intersection of artificial intelligence and blockchain technology is fundamentally restructuring how capital markets operate. Financial institutions and decentralized protocols are moving beyond simple digital asset issuance to build complex, intelligent systems that manage themselves. Tokenization creates a digital, programmable representation of real-world assets, generating massive amounts of on-chain data. However, human operators cannot process this transaction volume fast enough to optimize investments or manage compliance at a global scale. The AI tokenization convergence solves this operational bottleneck by pairing machine learning’s analytical power with blockchain’s immutable ledger.
This analysis explores how autonomous agents execute trades, how machine learning models automate regulatory compliance, and how predictive analytics assess risk across tokenized real-world assets. Understanding this technological overlap is necessary for market participants who want to survive the next phase of digital capital markets. Institutions that fail to integrate artificial intelligence into their tokenization infrastructure will find themselves unable to compete with the speed, efficiency, and cost reductions achieved by automated platforms. We will examine the specific mechanics of this convergence, the platforms currently deploying these models in production, and the severe regulatory risks that accompany algorithmic financial autonomy.
Context behind the foundation of AI and tokenization
The AI tokenization convergence represents the integration of machine learning algorithms with blockchain-based asset representation. Tokenization generates rich, programmable on-chain data, while artificial intelligence provides the computational power to process these large datasets, identify patterns, and automate complex financial decisions across global jurisdictions.
Artificial intelligence and blockchain infrastructure function as highly complementary technologies that solve each other’s structural limitations. Blockchain networks provide transparent, verifiable, and immutable data trails, which are exactly what machine learning models require for accurate training and execution. Conversely, artificial intelligence provides the cognitive processing power needed to make sense of the overwhelming volume of data generated by global tokenized markets. When you understand what is asset tokenization, you realize it simply creates a digital wrapper around an asset, but it does not inherently make that asset intelligent. By applying natural language processing and machine learning to these digital wrappers, developers create financial instruments that can monitor their own compliance, adjust their pricing based on external data feeds, and interact with other assets autonomously. This combination creates a market environment where capital moves with unprecedented frictionlessness, guided by data-driven algorithms rather than human intermediaries.
This convergence also operates in reverse, as the blockchain industry begins tokenizing artificial intelligence infrastructure and compute resources. Graphic processing unit compute power is currently being tokenized by platforms like Render Network and Akash Network, allowing retail and institutional participants to hold fractional ownership of decentralized infrastructure. Render Network and Akash Network have established market capitalizations in the hundreds of millions to billions of dollars by facilitating decentralized compute marketplaces where AI developers can rent processing power paid for in tokens. Beyond hardware, developers are exploring the tokenization of machine learning model weights as intellectual property assets, allowing creators to monetize specific algorithms through fractional ownership. Training data marketplaces are also emerging where tokenized data rights ensure contributors are compensated when their information is used to train commercial AI models. This bidirectional relationship means AI improves tokenized markets while tokenization democratizes access to AI development resources.
Understanding the tokenization market size requires looking at how these two technologies compound each other’s growth. A tokenized real estate fund without AI requires human analysts to monitor market conditions, manual compliance officers to check investor accreditations, and traditional brokers to find liquidity. The same fund powered by artificial intelligence operates with a fraction of the overhead, automatically updating property valuations using satellite imagery and matching buyers with sellers through algorithmic market making. This operational efficiency drastically lowers the barrier to entry for asset issuers, suggesting that the total addressable market for digital assets will expand much faster than models relying on traditional financial infrastructure predict. The programmable nature of smart contracts provides the perfect execution environment for AI decisions, creating a closed-loop system where data analysis immediately translates into on-chain financial execution.
What happened when platforms automated compliance and analytics
Developers integrated artificial intelligence into tokenization platforms to automate compliance and build predictive analytics models for real-world assets. Machine learning algorithms now handle KYC screening, transaction monitoring, and regulatory reporting, effectively reducing compliance operations that traditionally consume 30% to 50% of a tokenization platform’s budget.
Compliance remains the single largest operational cost center for platforms issuing digital securities, requiring armies of analysts to manually review flagged transactions and verify investor identities. Artificial intelligence automates this burden through machine learning models that analyze identity documents, cross-reference global sanctions lists, and assess risk profiles in seconds rather than hours. Firms like Chainalysis, Elliptic, and TRM Labs already deploy advanced blockchain analytics to monitor cryptocurrency transactions for suspicious patterns. Extending these existing capabilities to tokenized securities adds a layer of securities law monitoring, ensuring that secondary market transfers do not violate lock-up periods or jurisdictional restrictions. Natural language processing models continuously monitor regulatory publications across more than 50 jurisdictions, immediately flagging legal changes that affect specific tokenized products. These systems can then automatically generate formatted compliance reports and route them directly to regulatory bodies like the SEC, ESMA, or MAS without human intervention.
Beyond compliance, machine learning models are fundamentally changing how investors evaluate what is RWA tokenization through predictive analytics. Real estate valuation models now process satellite imagery, local demographic shifts, macroeconomic indicators, and historical blockchain transaction data to predict tokenized property values with high accuracy. In the fixed income sector, yield prediction models forecast returns across tokenized debt products based on interest rate projections, credit spreads, and platform-specific risk factors. Market microstructure models analyze order book data across decentralized exchanges to predict liquidity crunches and determine optimal execution strategies for large block trades of tokenized securities. These analytics tools transform opaque real-world assets into transparent, data-rich investment vehicles where risk can be quantified and priced in real-time.
Credit risk assessment for tokenized private credit pools represents one of the most successful production use cases for these analytical models. Traditional credit scoring relies on established banking histories, which excludes massive populations in emerging markets from accessing capital. Platforms deploy machine learning to analyze alternative data sources, including mobile phone usage patterns, utility payment histories, and social connections, to assess default probability in underbanked regions. By feeding this alternative data into predictive models, decentralized credit protocols can confidently underwrite loans to businesses that traditional banks would reject. This application of artificial intelligence directly expands the reach of tokenized capital, proving that algorithmic risk assessment can outperform traditional human underwriting in specific market segments.
Results from deploying autonomous agents and smart protocols
The deployment of AI-driven tokenization protocols has resulted in autonomous portfolio managers and advanced credit scoring systems. Platforms use machine learning to assess alternative credit data, while infrastructure networks enable autonomous AI agents to negotiate and execute tokenized asset trades without human intervention.
Artificial intelligence is rapidly changing how capital is deployed across digital asset ecosystems through the introduction of smart investing protocols. Robo-advisors designed specifically for tokenized portfolios use machine learning models to construct optimal asset allocations based on precise investor risk profiles. These systems take advantage of the 24/7 nature of blockchain markets to automatically rebalance portfolios and execute tax-loss harvesting strategies at any hour, a capability traditional financial advisors cannot match. When reviewing platforms in the space, such as an Ondo Finance review, it becomes clear that integrating sentiment analysis provides a massive edge. Natural language processing models monitor social media velocity, news sentiment, and on-chain whale movements to gauge market psychology for specific tokenized asset categories, allowing algorithmic funds to front-run human panic or exuberance.
Decentralized lending protocols have already proven the viability of AI-driven credit scoring in production environments. Goldfinch and similar private credit platforms utilize alternative data and machine learning models to assess borrower creditworthiness in emerging markets where traditional FICO scores do not exist. These models analyze business cash flows, local economic indicators, and repayment histories to generate dynamic credit scores that update with every on-chain interaction. This results in capital flowing from decentralized finance investors in developed nations directly to verified businesses in emerging markets, with the AI model acting as the trusted underwriter. The success of these alternative credit models demonstrates how how tokenization works in practice when paired with intelligent risk assessment, bridging the gap between decentralized liquidity and real-world economic activity.
The most aggressive advancement in this sector is the emergence of AI agents that autonomously transact with tokenized assets. Autonomous portfolio managers are AI agents granted limited wallet access that can execute trades, manage collateral positions, and optimize yield across various decentralized protocols without human approval. AI-driven market making agents provide liquidity for tokenized securities, dynamically adjusting bid-ask spreads based on real-time risk assessments and inventory levels. We are now seeing the foundation for agent-to-agent transactions, where an AI acting on behalf of an institutional investor negotiates a bilateral trade of tokenized assets with another AI agent. Infrastructure projects like Fetch.ai and Autonolas are actively building the decentralized frameworks required for these AI agents to operate securely within DeFi environments, creating a new paradigm where software acts as both the asset and the trader.
Lessons learned managing algorithmic risks and regulations
The primary lesson from merging artificial intelligence with tokenized assets is that algorithmic autonomy introduces severe compliance and systemic risks. Financial regulators require explainable decision-making, meaning platforms must balance advanced machine learning capabilities with strict regulatory frameworks to avoid catastrophic market failures.
Giving AI agents control over financial assets introduces new categories of risk that traditional financial regulations were not designed to handle. The most prominent issue is black box risk, where AI-driven investment decisions in tokenized assets become too complex for human operators to explain. Financial regulators generally require explainable AI for financial decisions to ensure that trading algorithms are not engaging in market manipulation or discriminatory practices. If an autonomous portfolio manager executes a series of trades that result in a flash crash for a tokenized security, the platform operators must be able to explain the exact parameters that triggered the event. Furthermore, AI models trained on historical data run the risk of perpetuating data bias, particularly in credit scoring and risk assessment applications, potentially violating fair lending laws if applied to tokenized private credit.
Systemic risk amplification presents a massive threat to the stability of AI-driven tokenized markets. If multiple institutional AI systems use similar foundational models and ingest the same data feeds, they may make highly correlated decisions during periods of market stress. A minor negative data point could trigger simultaneous automated sell orders across dozens of autonomous agents, wiping out the liquidity of a tokenized asset in milliseconds. This algorithmic herding behavior removes the diverse human opinions that traditionally stabilize financial markets during panics. Market operators must design circuit breakers and volatility interruptions specifically tailored to manage autonomous agent behavior, recognizing that software reacts exponentially faster than human traders.
Regulatory uncertainty remains the largest barrier to the full realization of the AI tokenization convergence. Neither artificial intelligence nor blockchain tokenization has fully mature regulatory frameworks globally, and their intersection is entirely undefined. The European Union’s AI Act imposes strict requirements on high-risk AI systems deployed in financial services, demanding rigorous transparency, human oversight, and detailed record-keeping. In the United States, recent SEC guidance regarding the use of predictive data analytics by broker-dealers and investment advisers requires firms to eliminate conflicts of interest embedded within their AI models. Anyone consulting a tokenization glossary will find that definitions of these technologies vary wildly between jurisdictions, making global compliance an intricate puzzle. Platforms must architect their AI systems to be highly modular, allowing them to adjust their algorithmic behavior to comply with the specific legal requirements of whatever jurisdiction a tokenized asset touches.
Frequently Asked Questions
How does AI reduce compliance costs for tokenization platforms?
Artificial intelligence reduces compliance costs by automating manual review processes using machine learning. These models analyze identity documents, cross-reference global sanctions lists, and monitor on-chain transactions for suspicious activity in real-time, cutting compliance expenses that normally consume 30% to 50% of operating budgets.
What are autonomous AI agents in tokenized markets?
Autonomous AI agents are software programs granted wallet access to execute trades and manage assets without human intervention. Infrastructure projects like Fetch.ai and Autonolas enable these agents to optimize yields, provide market liquidity, and negotiate bilateral trades across decentralized finance protocols.
How do predictive analytics evaluate tokenized real estate?
Predictive analytics evaluate tokenized real estate by processing massive datasets including satellite imagery, local demographic shifts, and macroeconomic indicators. Machine learning models synthesize this alternative data alongside historical blockchain transactions to generate highly accurate, real-time property valuations for digital asset investors.
What regulatory risks exist when combining AI and tokenization?
The primary regulatory risk is black box decision-making where AI investment choices cannot be clearly explained to regulators. Frameworks like the EU AI Act and SEC predictive data analytics guidance require financial platforms to maintain human oversight, eliminate algorithmic conflicts of interest, and ensure explainability.