RWA Tokenization 100 Billion Impact: Market Structure Shifts
The financial industry treats tokenized real-world assets as a promising experiment, but the mathematical trajectory points toward an impending structural shift. As total value locked in tokenized assets climbs steadily upward, market participants must model what happens when this asset class crosses the systemic threshold. The RWA tokenization 100 billion impact will fundamentally alter market structure, forcing traditional institutions to adapt and regulators to intervene. Reaching a hundred billion tokenized assets is not merely a psychological milestone; it is the exact point where tokenization transitions from an isolated sandbox into a load-bearing pillar of the global financial system. This analysis examines the mechanics of that transition, evaluating how deep liquidity, regulatory oversight, and complex composability will reshape capital markets when digital assets achieve critical mass.
The trajectory toward a hundred billion tokenized assets
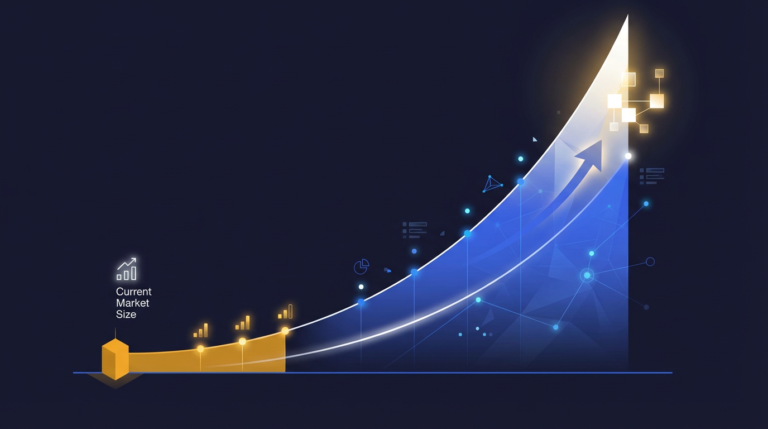
The current tokenization market holds approximately $10 billion to $15 billion in total value locked, driven by rapid growth in tokenized treasuries and private credit. Reaching the $100 billion threshold will require sustained triple-digit annual growth, mirroring the historical adoption curve of exchange-traded funds in the early 2000s.
As of early 2026, the baseline infrastructure for tokenized markets is fully operational, supporting a total value locked of $10 billion to $15 billion excluding stablecoins. This capitalization breaks down into distinct asset classes, with tokenized private credit dominating at over $8 billion and tokenized United States Treasuries exceeding $2 billion. Other categories like tokenized real estate currently range between $500 million and $1 billion, while tokenized commodities account for another $1 billion in value. These figures reflect a foundational phase where early adopters establish the legal and technical rails required for institutional participation. Growth rates for the fastest-expanding categories consistently track between 100% and 200% year-over-year. This suggests the market could realistically breach the $100 billion mark by 2028 if current adoption vectors hold steady. Understanding this tokenization market size analysis requires looking beyond the raw numbers to the underlying institutional confidence that drives capital allocation.
The historical parallel for this growth trajectory is the exchange-traded fund market, which provides a clear blueprint for how novel financial structures achieve systemic scale. According to historical data from the Investment Company Institute, the ETF market required 13 years to grow from absolute zero in 1993 to its first $100 billion in assets under management by 2006. Once that liquidity threshold was crossed, the compounding effects of market confidence and structural efficiency accelerated adoption dramatically. The ETF market surged to $1 trillion by 2012 and eventually pushed past $10 trillion today. For those asking what is RWA tokenization in a macro context, it is simply the next iteration of this exact packaging and distribution evolution. The $100 billion milestone matters because it is the minimum viable scale required for major asset managers to justify the fixed costs of overhauling their legacy settlement systems.
What happens at $100 billion: Integration and market structure shifts
At $100 billion in tokenized assets, market structure shifts fundamentally as traditional prime brokers enter the space and secondary market liquidity deepens. Decentralized finance protocols will simultaneously transition away from volatile crypto collateral, using tokenized treasuries and private credit to build sustainable, yield-bearing structured products.
The RWA market structure effects at the $100 billion level will force traditional financial institutions to move from defensive observation to active integration. Prime brokerages at institutions like Goldman Sachs, Morgan Stanley, and JPMorgan will begin offering aggressive margin lending against tokenized securities. They will treat these instruments as standard collateral rather than exotic digital assets. Rating agencies including Moody’s, S&P, and Fitch will deploy standardized rating methodologies for tokenized instruments, allowing conservative institutional mandates to allocate capital safely. Financial data providers like Bloomberg and Refinitiv will integrate comprehensive tokenized asset data feeds directly into their terminals, normalizing the pricing and volume metrics alongside traditional equities and bonds. We are already seeing the precursors to this integration with products like the BlackRock USD Institutional Digital Liquidity Fund. Studying a BlackRock BUIDL fund analysis reveals exactly how asset managers plan to distribute tokenized mutual funds to retail and institutional clients at scale.
Secondary market liquidity will undergo a radical transformation once the market capitalization provides enough volume to support professional market makers. Currently, tokenized asset trading relies heavily on automated market makers and niche liquidity providers, resulting in wide spreads and limited depth. At $100 billion, high-frequency trading firms and traditional market makers will deploy dedicated capital to these order books. This will narrow bid-ask spreads significantly and create a highly efficient price discovery mechanism. This deep liquidity will catalyze the emergence of robust derivatives markets, including futures and options on tokenized real estate indices or interest rate swaps based on tokenized bond yields. The theoretical liquidity premium often cited in discussions about how tokenization works will finally materialize as a measurable reduction in the illiquidity discounts historically applied to private market assets. The settlement efficiency of blockchain networks will rival traditional clearinghouses, matching the Depository Trust & Clearing Corporation’s ability to reduce settlement obligations by over 98% through multilateral netting.
The decentralized finance ecosystem will experience an equally profound structural shift as $100 billion in high-quality tokenized collateral becomes available on-chain. Historically, DeFi lending markets have relied on highly volatile crypto-native assets like Ethereum or wrapped Bitcoin to function. This dynamic requires massive overcollateralization to prevent cascading liquidations during sudden market downturns, severely limiting capital efficiency. The injection of tokenized treasuries and investment-grade corporate debt will replace this volatile foundation with stable, yield-bearing collateral. This shift fundamentally alters the risk profile of decentralized lending by grounding it in sovereign and corporate credit. Protocol emission yields will be fully replaced by the real yield generated from underlying traditional assets. Developers will build complex structured products on top of these foundations. These products will offer leveraged yield strategies on tokenized treasuries or automated fixed-income portfolios that rebalance based on macroeconomic indicators. Insurance protocols will also scale up their operations, utilizing the deep pools of tokenized reserve assets to underwrite larger and more comprehensive policies for both on-chain smart contract failures and off-chain real-world events.
Systemic risks and the regulatory response at scale
Reaching $100 billion in tokenized assets will trigger comprehensive regulatory intervention, including mandatory reporting requirements and potential systemic risk designations. This scale also introduces new vulnerabilities to the financial system, specifically regarding smart contract exploits, oracle network dependencies, and concentrated stablecoin settlement risks.
The tokenized assets systemic impact at this scale will end the current period of regulatory forbearance and trigger aggressive oversight from global authorities. Regulators will implement mandatory reporting requirements for tokenized asset platforms. This will likely mirror the Form 13F filings that currently require institutional investment managers with over $100 million in qualifying equities to disclose their holdings. The largest tokenization platforms and settlement networks will face intense scrutiny and may receive designation as Systemically Important Financial Market Utilities under Title VIII of the Dodd-Frank Act. This SIFMU designation brings stringent risk management standards, mandatory stress testing, and direct oversight from the Federal Reserve, fundamentally changing the operating economics for tokenization infrastructure providers. Cross-border regulatory coordination will also formalize. Organizations like the International Organization of Securities Commissions and the Financial Stability Board will establish unified frameworks to prevent regulatory arbitrage. Reviewing a comprehensive tokenization glossary shows how quickly the legal terminology is evolving to capture these new digital market structures.
This massive accumulation of capital on blockchain networks introduces entirely new vectors for systemic financial risk that regulators and institutions must mitigate. Smart contract vulnerabilities transition from isolated protocol risks to broader financial stability concerns. A single critical bug in a widely adopted token standard could instantly freeze or drain billions of dollars in collateral. Oracle dependency creates a severe single point of failure. Networks like Chainlink currently maintain exceptional uptime statistics, but a prolonged disruption would halt net asset value calculations and freeze lending liquidations across hundreds of interconnected protocols. Cross-chain bridge infrastructure presents another massive vulnerability, as the movement of tokenized assets between different blockchain environments creates honeypots of locked capital susceptible to sophisticated exploits. Most critically, the overwhelming reliance on USDC and USDT for settlement creates a massive concentration risk tied directly to the reserve management practices of stablecoin issuers. Investors must carefully evaluate these tokenized asset risks because an on-chain failure at the $100 billion scale will inevitably propagate back into traditional financial markets through shared institutional balance sheets.
The compounding effect toward a trillion-dollar market
The $100 billion threshold is the catalyst for exponential growth toward a $1 trillion tokenized asset market. Network effects, mature institutional infrastructure, and definitive regulatory clarity will combine to accelerate adoption, forcing remaining traditional financial institutions to enter the space aggressively.
The most critical lesson from modeling the RWA tokenization 100 billion impact is that this threshold is the point where linear growth becomes exponential. Network effects take full control at this stage. The presence of deep liquidity attracts more institutional participants, which in turn deepens the liquidity further in a self-reinforcing cycle. The institutional-grade infrastructure built to handle the first $100 billion will scale seamlessly to support a trillion-dollar market without requiring proportional increases in operational overhead. This includes qualified custody solutions, identity verification networks, and automated compliance engines. Regulatory clarity, forged through the friction of reaching the initial milestone, will provide the definitive legal certainty that highly conservative pension funds and sovereign wealth funds require before deploying capital. This compounding effect guarantees that the journey from $100 billion to $1 trillion will take a fraction of the time required to build the initial market foundation.
Traditional finance will experience overwhelming competitive pressure as the efficiencies of tokenization become impossible to ignore at scale. Institutions that maintained a cautious, observational stance during the early growth phases will face severe margin compression if they continue relying on legacy settlement infrastructure while their competitors utilize instant on-chain clearing. This dynamic will trigger a wave of aggressive acquisitions. Major banks will buy up successful tokenization startups and infrastructure providers to quickly close the technology gap. The tokenization reaching scale will ultimately erase the artificial boundary between traditional finance and digital assets. This integration results in a unified financial system where the underlying blockchain rails become as invisible and ubiquitous as the internet protocols routing today’s digital communications. Market participants who successfully navigate the systemic risks and regulatory adjustments of the $100 billion threshold will position themselves to capture the vast majority of the value generated during the subsequent expansion to $1 trillion.
Reaching $100 billion in tokenized real-world assets will permanently alter the mechanics of global capital markets. The integration of blockchain settlement with traditional financial assets creates unprecedented efficiencies, but it also introduces complex systemic vulnerabilities that require rigorous new regulatory frameworks. As prime brokers, market makers, and asset managers adapt to this high-liquidity environment, the structural advantages of tokenization will become the baseline expectation for all financial transactions. Institutions must begin upgrading their technological infrastructure and risk management protocols immediately to prepare for this inevitable market transition.
Frequently Asked Questions
What is the current market size of tokenized real-world assets?
The current market size of tokenized real-world assets is approximately $10 billion to $15 billion in total value locked, excluding stablecoins. Tokenized private credit accounts for over $8 billion, while tokenized United States Treasuries represent more than $2 billion of this total.
How fast is the RWA tokenization market growing?
The fastest-growing categories within the RWA tokenization market are expanding at rates between 100% and 200% year-over-year. If this trajectory holds steady, the total market capitalization for tokenized assets could reach the $100 billion threshold by the year 2028.
What regulatory changes will happen when tokenization reaches $100 billion?
Regulators will likely implement mandatory reporting requirements similar to Form 13F for institutional holders of tokenized assets. The largest tokenization platforms may also receive Systemically Important Financial Market Utility designations under the Dodd-Frank Act, subjecting them to Federal Reserve oversight.
How will $100 billion in tokenized assets affect decentralized finance?
High-quality tokenized assets will replace volatile cryptocurrencies as the primary collateral in decentralized finance lending markets. This shift will allow DeFi protocols to offer sustainable real yield generated from traditional assets rather than relying on inflationary token emission schedules.
What are the main systemic risks of tokenized assets at scale?
The primary systemic risks include smart contract vulnerabilities, heavy reliance on oracle networks like Chainlink for pricing data, and concentration risk in stablecoin settlement. A technical failure at the $100 billion scale could propagate directly into traditional financial markets.
Sources
- [1] 2023 Investment Company Fact Book: A Review of Trends and Activities in the Investment Company Industry
- [2] Advancing the Digital Asset Era: Settlement and Netting Efficiency
- [3] Form 13F – Reports Filed by Institutional Investment Managers
- [4] Designated Financial Market Utilities (Title VIII of Dodd-Frank)
- [5] Regulation, Supervision and Oversight of Crypto-Asset Activities and Markets