Will Tokenization Replace Stock Exchanges? DLT vs TradFi
Financial markets are undergoing a fundamental infrastructure review as distributed ledger technology matures from a theoretical concept into an operational utility. The central question dominating capital markets technology discussions is whether will tokenization replace stock exchanges entirely, or if these two distinct architectures will merge into a hybrid model. Proponents of blockchain technology argue that decentralized ledgers offer a fundamentally superior way to issue, trade, and settle securities without the friction of traditional intermediaries. Incumbent exchange operators counter that their existing centralized matching engines provide unmatched speed, liquidity, and regulatory certainty that blockchains simply cannot replicate at scale. This analysis examines the technical realities, regulatory experiments, and institutional pilot programs shaping the future of global equity markets. Readers will learn how major financial institutions are deploying digital asset infrastructure, why certain high-profile blockchain migrations have failed, and what the actual stock exchange of 2030 will look like for investors and issuers.
The Clash Between Decentralized Ledgers and Wall Street
Tokenization will not completely replace stock exchanges in the near term, but it will fundamentally restructure how they operate. While traditional centralized matching engines remain vastly superior for high-frequency price discovery, distributed ledger technology is actively replacing legacy post-trade settlement systems, clearinghouses, and custodial infrastructure to reduce capital inefficiencies.
The argument that a DLT stock exchange replacement is inevitable rests on the severe inefficiencies embedded in current post-trade infrastructure. Traditional securities transactions require a complex chain of broker-dealers, clearinghouses, transfer agents, and custodians to execute and settle a single trade. This intermediary friction traps immense amounts of capital, as evidenced by the Depository Trust & Clearing Corporation (DTCC), which processes approximately $2.4 quadrillion in securities transactions annually. Blockchain advocates point out that moving these assets to a distributed ledger enables instant T+0 settlement, eliminating the counterparty risk that necessitates expensive clearinghouse margin requirements. Furthermore, smart contracts introduce programmable compliance, allowing issuers to automate know-your-customer checks, enforce transfer restrictions, and handle corporate actions like dividend distributions without manual reconciliation. If you want to understand what is asset tokenization, it fundamentally involves replacing these fragmented database silos with a single shared ledger that acts as the immutable golden record of ownership.
Skeptics maintain that existing market infrastructure already functions with remarkable efficiency and that ripping out decades of proven technology introduces unacceptable systemic risks. Centralized exchanges provide near-instant electronic matching where orders execute in microseconds, a feat that current blockchain architecture cannot replicate. To put the scale into perspective, US equity markets routinely process daily trading volumes exceeding 9 billion shares, requiring an infrastructure capable of handling massive throughput spikes during volatile periods. Furthermore, the intermediary layers that blockchain seeks to eliminate actually serve critical market functions. Clearinghouses provide multilateral netting, which effectively reduces the actual capital settlement obligations between counterparties by more than 98 percent on a typical trading day. This netting process drastically lowers systemic risk and capital requirements across the financial system, a feature that pure atomic settlement on a blockchain bypasses entirely.
The technical barriers preventing a complete blockchain vs stock exchange takeover remain substantial, particularly regarding throughput and deterministic finality. The Ethereum layer-1 network currently processes approximately 15 to 30 transactions per second, which pales in comparison to the New York Stock Exchange’s capacity to handle more than 1 million messages per second during peak trading. While layer-2 scaling solutions like Arbitrum and Optimism improve throughput significantly, they introduce new complexities regarding bridge security and fragmented liquidity. Additionally, public blockchain networks suffer from Maximal Extractable Value (MEV) vulnerabilities, where validators can front-run or sandwich retail trades by reordering transactions within a block. Traditional exchanges strictly prohibit this behavior through rigorous market surveillance and deterministic matching rules based on strict price-time priority. Network reliability also remains a critical concern, as any downtime would be catastrophic for a primary national securities exchange operating in a regulated environment. Learning how tokenization works at a technical level reveals that consensus mechanisms inherently trade speed for decentralization, a tradeoff that high-frequency trading firms are unwilling to accept.
Real-World Testing and the ASX CHESS Failure
Global regulators and exchange operators have moved beyond theoretical debates to conduct live experiments with tokenized market infrastructure. The results demonstrate that while DLT excels at parallel asset issuance and bilateral settlement, attempting to force complex, high-volume centralized clearing operations onto a blockchain often leads to costly technical failures and project cancellations.
The most prominent cautionary tale in the tokenized equities exchange narrative is the Australian Securities Exchange (ASX) and its failed attempt to replace its legacy CHESS clearing and settlement system with a blockchain-based alternative. Initiated in 2017 in partnership with Digital Asset, the project aimed to create the world’s first fully distributed ledger-based national clearing system. After five years of persistent delays, technical restructuring, and mounting industry frustration, the ASX abruptly canceled the project in late 2022. The exchange was forced to take a massive AUD $250 million write-off, acknowledging that the bespoke blockchain solution could not meet the scalability, latency, and operational requirements of a modern equities market. Independent reviews of the failure highlighted that applying decentralized consensus mechanisms to inherently centralized market functions created unnecessary friction and unmanageable software complexity. This high-profile collapse forced exchanges globally to reevaluate their digital asset strategies, shifting away from wholesale infrastructure replacement toward targeted, parallel implementations.
Conversely, European regulators have taken a structured, experimental approach to answering whether a future stock market blockchain is viable. The EU DLT Pilot Regime (Regulation 2022/858), which became effective in March 2023, represents the most significant regulatory sandbox for tokenized securities globally. This framework allows authorized financial institutions to operate DLT-based market infrastructure-specifically DLT Multilateral Trading Facilities (MTFs), DLT Settlement Systems (SS), and combined DLT Trading and Settlement Systems (TSS)-for up to six years with specific regulatory exemptions. To contain systemic risk, the regime imposes strict volume caps, limiting the total market capitalization of DLT financial instruments on any single platform to EUR 9 billion, and capping single equity instruments at EUR 500 million. This controlled environment provides regulators with empirical data on how smart contracts execute corporate actions, how DLT handles settlement finality, and whether retail investors can safely interact with tokenized securities without traditional broker-dealer intermediaries.
Rather than attempting a risky hard fork of existing systems, successful implementations have focused on building parallel digital infrastructure. The SIX Digital Exchange (SDX) in Switzerland provides the clearest example of this operational model. Operating as a fully regulated DLT-based exchange and central securities depository, SDX runs alongside the traditional SIX Swiss Exchange rather than replacing it. SDX has successfully facilitated the issuance of digital bonds for major financial institutions, including UBS and the City of Lugano, proving that institutional-grade tokenization functions perfectly well in a ring-fenced environment. By maintaining both systems, SIX allows market participants to choose their preferred issuance and settlement rails based on the specific requirements of the asset. This parallel approach aligns with broader what is RWA tokenization trends, where novel asset classes utilize blockchain rails while highly liquid traditional equities remain on legacy matching engines until the newer technology proves its absolute resilience.
The Convergence of Traditional Exchanges and DLT
The industry is clearly moving toward a convergence model rather than wholesale replacement. Major exchange operators are integrating distributed ledger technology into specific verticals like private market issuance, digital bond settlement, and collateral management while firmly retaining their proprietary, high-speed matching engines for public equity price discovery.
The world’s largest exchange groups are actively building digital asset divisions that treat blockchain as an underlying database upgrade rather than an existential threat. The London Stock Exchange Group (LSEG) has publicly outlined plans to build a bespoke digital markets business, specifically emphasizing that it will not build a crypto exchange, but rather a regulated venue using blockchain to improve the efficiency of trading traditional financial assets. Similarly, Nasdaq has developed its Digital Asset Suite, providing institutional-grade custody and settlement technology to other market operators. While Nasdaq paused its proprietary digital asset custodian plans due to regulatory uncertainty in the United States, the company continues to develop DLT-based clearing capabilities for private markets and carbon credit trading. These strategic moves indicate that incumbent operators view the expanding tokenization market size as a revenue opportunity rather than a disruptive force that will render their business models obsolete.
Other institutional giants are focusing their DLT efforts strictly on the post-trade and issuance lifecycle. Deutsche Boerse launched its D7 platform, a digital post-trade infrastructure that allows market participants to issue electronic securities seamlessly. The D7 platform handles digital bond issuance and connects directly to traditional settlement systems, proving that DLT can modernize the primary market without disrupting secondary market liquidity. Meanwhile, CME Group is exploring the use of tokenized assets, such as tokenized money market funds, as eligible collateral for margin requirements. This specific use case demonstrates how tokenization solves real institutional pain points-in this case, the velocity of collateral mobility-without requiring the underlying derivative contracts to trade on a decentralized ledger. When evaluating platforms in this space, as seen in our Centrifuge review, the most successful protocols are those that build compliant bridges to traditional finance rather than attempting to circumvent regulatory frameworks entirely.
The Hybrid Future of Global Capital Markets
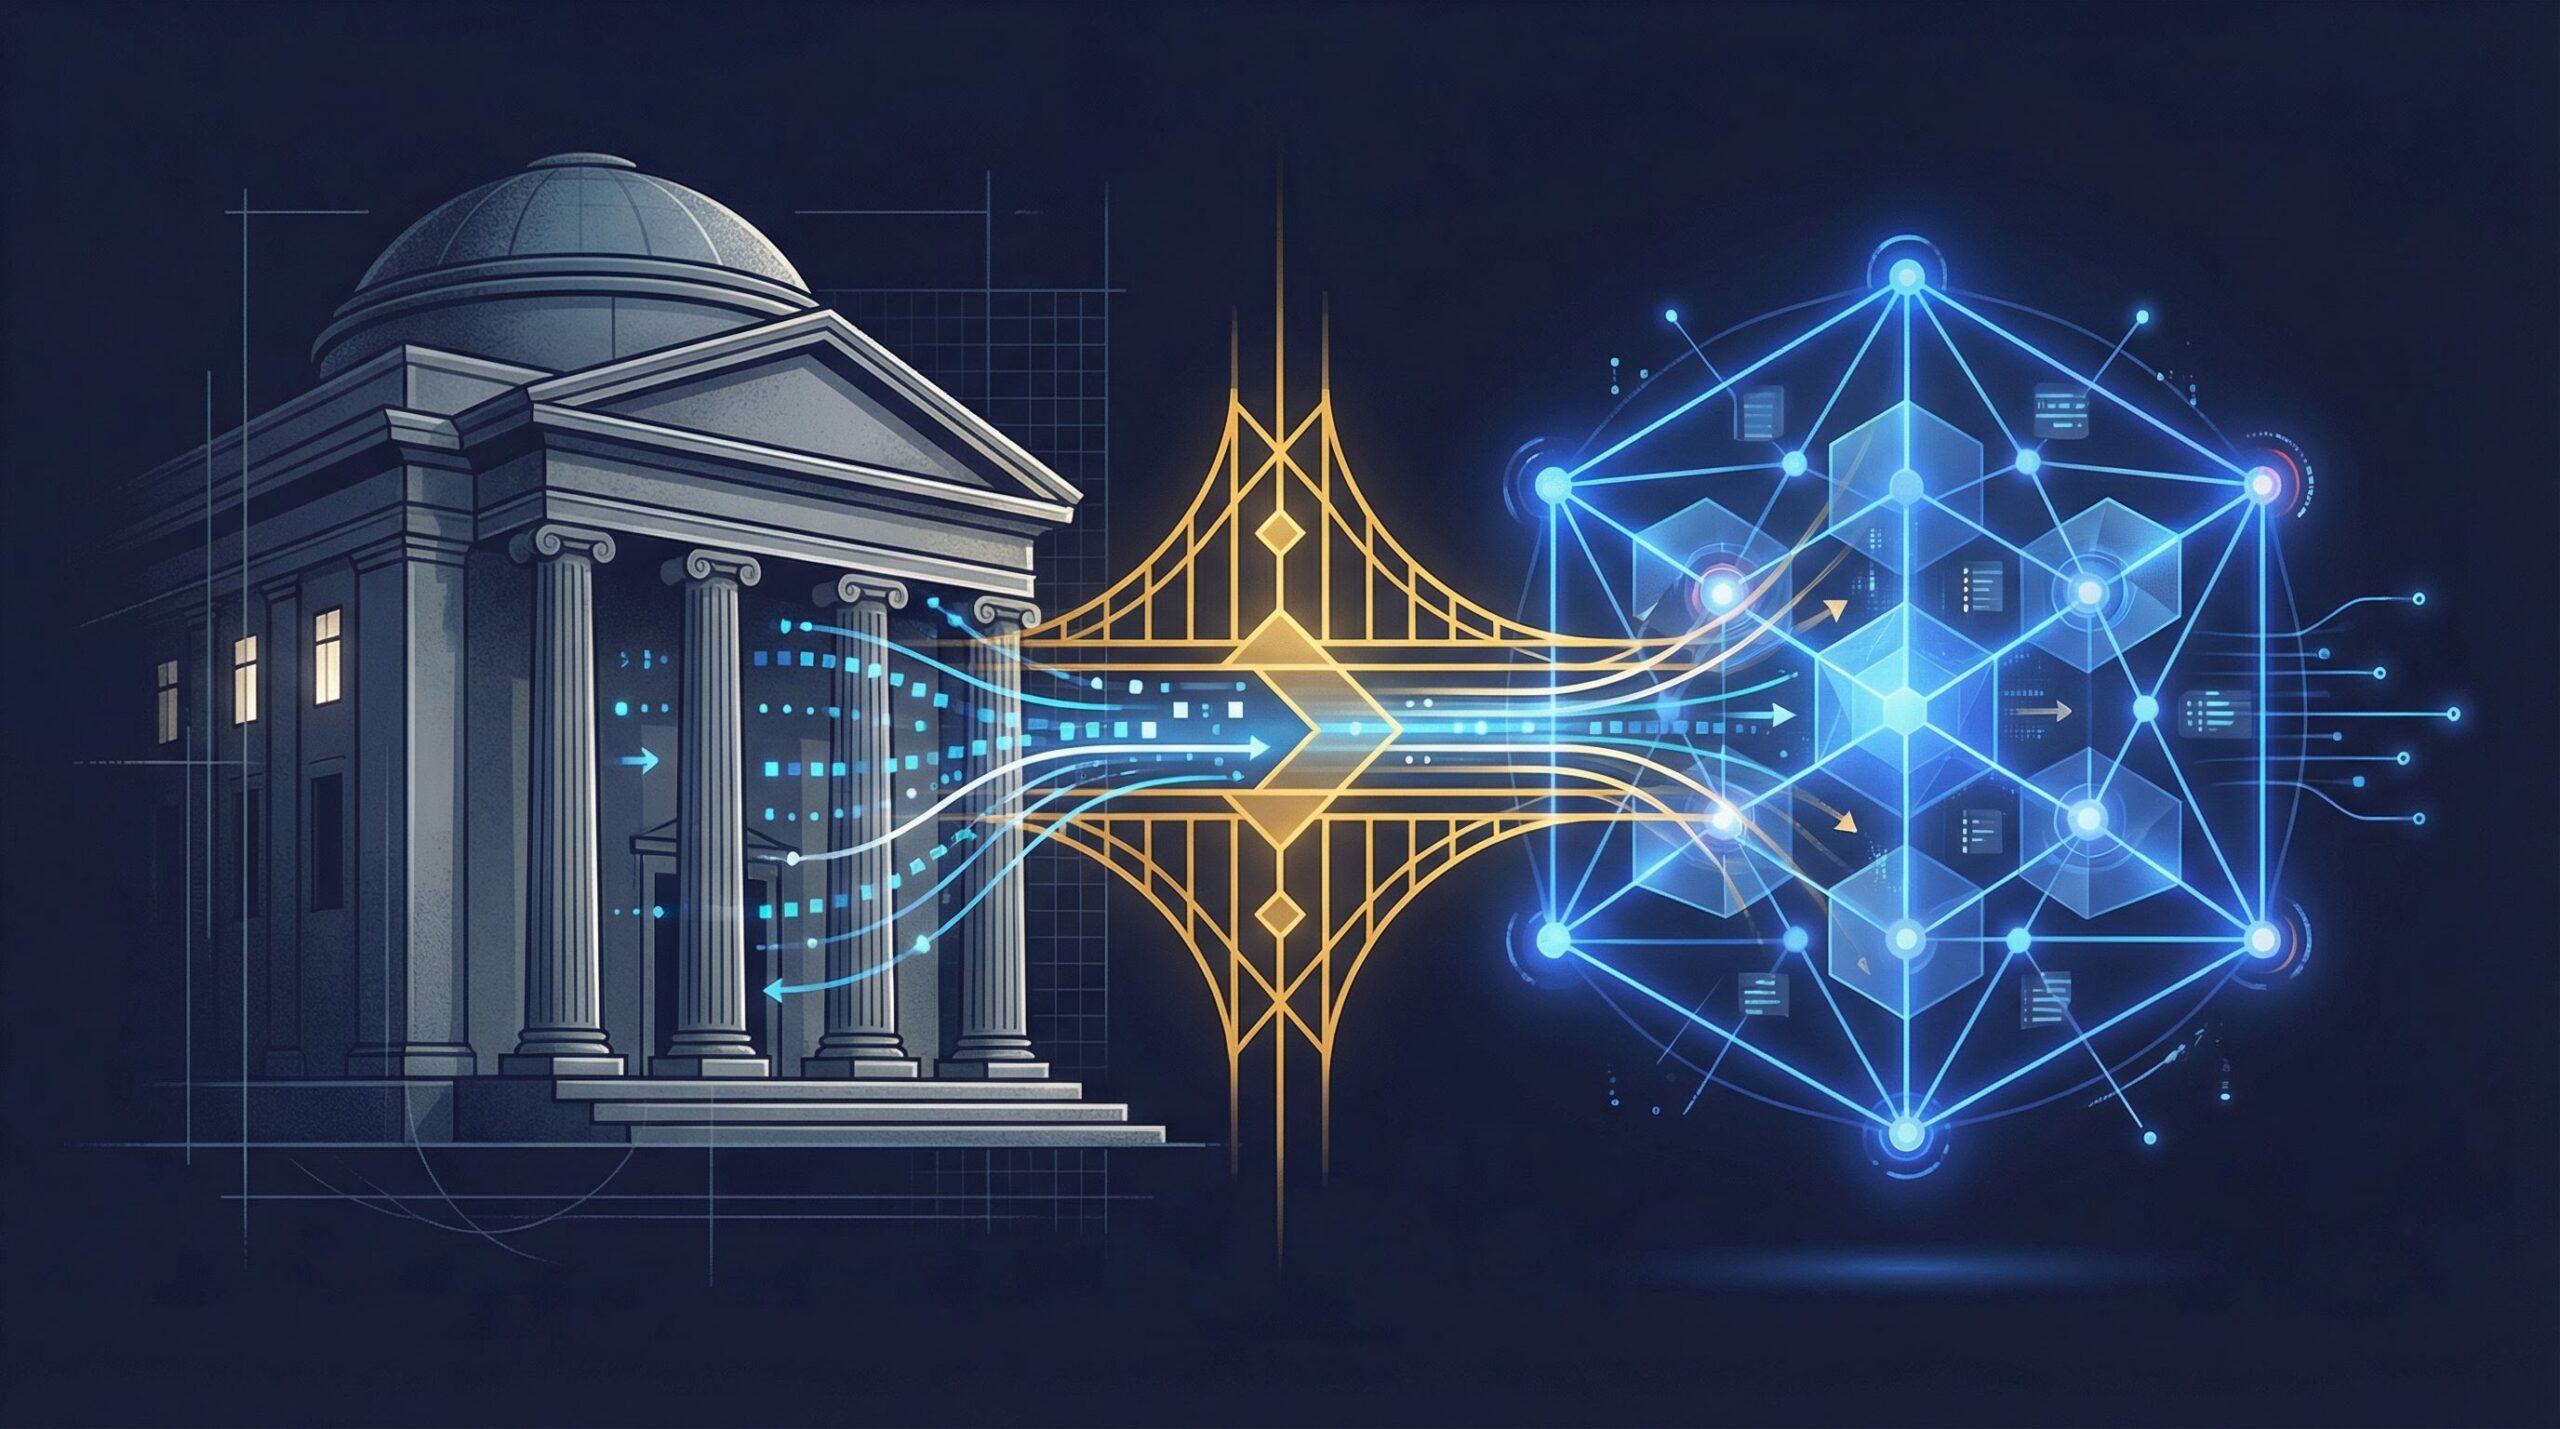
By 2030, global capital markets will operate on a hybrid infrastructure. Centralized order matching engines will continue to handle high-frequency trading and price discovery, while distributed ledgers will process the underlying settlement, manage corporate actions, and maintain the immutable cap tables for both public and private assets.
The financial infrastructure of the next decade will successfully merge the raw speed of centralized databases with the transparent, programmable nature of blockchain networks. Traditional order matching engines will remain the core venues for price discovery because they are mathematically superior at processing millions of sequential orders per second. However, once a trade executes on the central limit order book, the resulting settlement instructions will route directly to a distributed ledger. This hybrid model preserves the deep liquidity and deterministic execution that institutional investors demand, while simultaneously delivering the atomic settlement and automated reconciliation promised by blockchain advocates. Market participants will no longer need to maintain separate, fragmented databases that require constant batch processing and reconciliation at the end of each trading day. Instead, a single shared state will update instantly upon trade execution, drastically reducing the operational overhead associated with middle and back-office functions.
This structural evolution carries profound implications for all market participants. For corporate issuers, integrating DLT into the primary issuance process will significantly reduce the cost and time required to list securities, potentially reversing the decades-long trend of companies staying private longer. Programmable cap tables will handle complex dividend distributions, voting rights, and compliance restrictions automatically through smart contracts, eliminating the need for expensive transfer agents. For retail and institutional investors, the competitive pressure from blockchain alternatives is already forcing traditional brokers to compress fees and accelerate settlement times, evidenced by the US market’s transition to T+1 settlement. As cross-border interoperability improves, investors will gain seamless access to foreign securities without navigating complex correspondent banking chains. To navigate these upcoming changes, professionals should familiarize themselves with essential tokenization glossary definitions, as the vocabulary of decentralized finance is rapidly becoming the standard language of institutional capital markets.
Frequently Asked Questions
Will tokenization replace stock exchanges completely?
Tokenization will not completely replace stock exchanges, but it will upgrade their underlying infrastructure. Traditional matching engines will remain for high-speed price discovery, while distributed ledgers will replace legacy clearinghouses and settlement systems to enable faster, cheaper post-trade processing.
Why did the ASX CHESS blockchain replacement fail?
The ASX CHESS replacement failed because applying decentralized consensus mechanisms to highly centralized, high-volume market functions created unmanageable software complexity. The project suffered from severe latency issues and scalability constraints, resulting in a project cancellation and an AUD $250 million write-off.
What is the EU DLT Pilot Regime?
The EU DLT Pilot Regime is a regulatory framework effective March 2023 that allows financial institutions to operate blockchain-based trading and settlement systems. It provides regulatory exemptions for up to six years, capped at EUR 9 billion in total market capitalization, to test DLT infrastructure safely.
Can Ethereum handle traditional stock market trading volumes?
Ethereum cannot currently handle traditional stock market volumes. The Ethereum layer-1 network processes roughly 15 to 30 transactions per second, which is vastly insufficient compared to the New York Stock Exchange, which regularly processes over 1 million messages per second during peak trading hours.